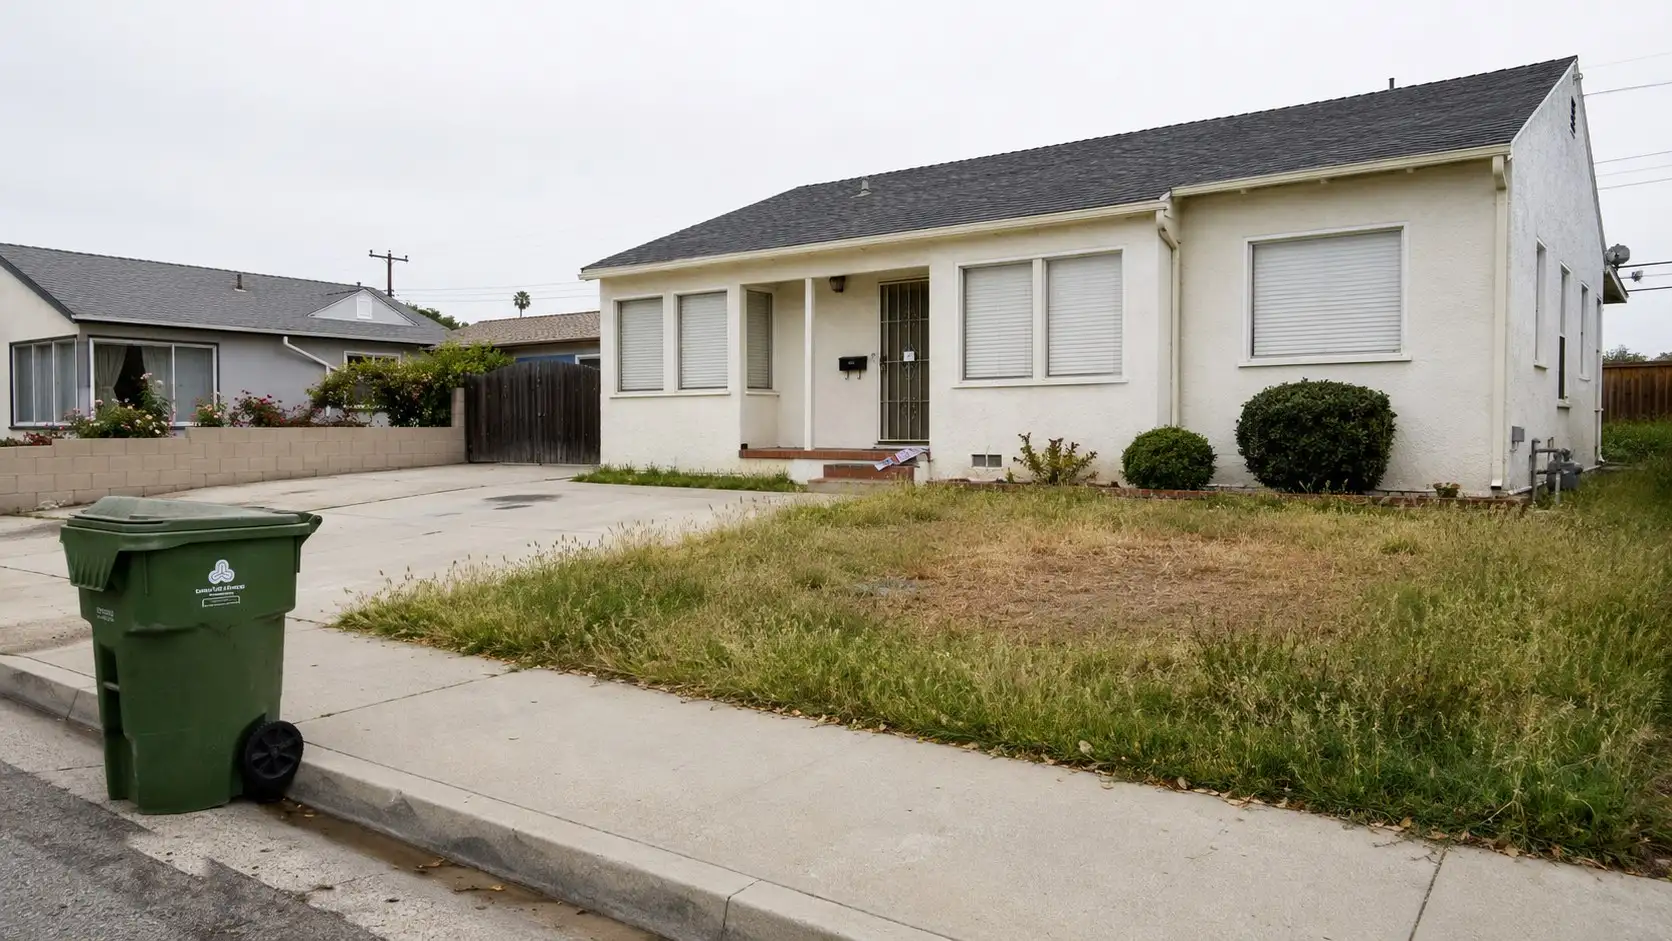
Sell your house for cash · Los Angeles

Facing foreclosure in Los Angeles?

A mortgage, taxes and insurance on a house you’re not living in. The back payments and the late fees come off at closing, out of the proceeds, not out of your pocket today. If there is equity left after the payoff, it is yours.

The letters stopped being about a missed payment and started being about a date. Most people I meet at this point have opened the last three without reading them.

The part nobody tells you: you can still sell your house before foreclosure runs its course, right up until the day the auction is scheduled for. What shrinks as it gets closer is the room to negotiate, not the option itself.

How this actually goes.

  1. You tell me about the house.

    A few questions, on the form or the phone: the address, what shape it’s in, what’s going on. Maisha usually picks up. Her job is to get me to your kitchen table, not to talk you into anything.

    Day 0 · a few questions

  2. I bring you all three numbers in writing.

    I walk it with Marco, who sells the houses I buy and sits in on every seller meeting. You get the comps, the repair estimate and all three numbers on the spot. Not a “let me run this by my team.”

    All three numbers, at the table

  3. You pick the path and the date.

    You choose, I execute. Cash closes in about 17 days at a local title company. On path two the renovation starts and I handle every contractor, permit, photo and showing.

    Cash closes in about 17 days

Every option you have, including the ones without me.

Most of the ways out of this do not involve me, and one of them usually pays more than I will. Here they are, in the order I would think about them if it were my house.

  1. Catch it up, or work something out with the lender

    If you can get current, or the lender will take a modification or a repayment plan, you keep the house. That beats everything below it. Call the lender's loss mitigation department, and call a HUD-approved housing counsellor. Nothing on this page is a reason to skip that call.

  2. List it on the open market with an agent

    Where there is equity and there is time, this is the one that usually pays the most. A house in foreclosure can be listed and sold like any other house, with the lender paid out of escrow at closing. What it costs you is time and certainty: showings, a buyer's loan, an appraisal, an inspection, and a closing date you do not fully control. Any agent can do this. It does not have to be me.

  3. A short sale, if you owe more than the house is worth

    When the debt is bigger than the value, a straight sale does not clear it. Short sale homes are sold with the lender's written approval to take less than the balance, and a short sale real estate agent negotiates that for you. It runs in months rather than weeks. I do not buy short sales as a rule, so this is one where I am not your buyer. Your lender and your attorney belong in that conversation before I do.

  4. Sell it at auction yourself

    The auction platforms will run a property on a set date, and the buyers there arrive with cash. It is fast, and the price is whatever the room pays that day. Some sellers like having a date they chose. Most people I meet do not want their address advertised while they are still living in it.

  5. Keep it and rent it out

    This only works if the loan gets current, because a tenant does not stop a foreclosure. If you have equity, a long horizon and the stomach to be a landlord in Los Angeles, keeping the house is a real answer. If the payment is already more than the rent, it is not.

  6. Do nothing and let the date arrive

    I will name it, because people choose it and sometimes it is the honest answer. Where there is no equity and no buyer, letting it go happens. What I would not do is arrive there by accident. Ask your attorney and a HUD-approved housing counsellor what that path means for you, then decide it on purpose.

  7. Sell it to me

    One number, signed, closing at a local title company in about 17 days, and the trade is that my number is lower than a finished house on the open market would bring. The arrears and the late fees come off at closing, out of the proceeds, not out of your pocket today, and if there is equity left after the payoff it is yours. I buy to resell at a profit, so that profit is inside the offer. It is worth it when the calendar is the problem. It is not worth it when you still have time.

All three numbers, applied to this.

Path one · the cash offer

One number, signed, closing at a local title company in about 17 days. When there is a date on the calendar, certainty is usually worth more than the last few thousand dollars.

What it costs you. Nothing. No commission, no repair credits, and no closing costs out of your pocket.
Path two · renovate and list

Only if the auction date leaves room for it. If it does not, I will tell you that instead of listing a house that will not sell in time.

What it costs you. My listing commission, and the renovation money comes back out of the sale proceeds at closing. Never out of your pocket.

Path three · built around your situation

Cash, funding or a listing, whichever the situation calls for. For when the house is not the actual problem.

What it costs you. Nothing up front. Whatever I advance, carry or pay for comes back out of the proceeds at closing, on terms you see before you sign.

Questions I get about this one.

Can I still sell if I have already received a notice of default?

Usually yes. A sale can close right up until the auction. Get me the notice and the payoff figure and I can tell you within a day whether the timeline works.

Can I sell my house before the auction in California?

Yes, and the window is wider than most people think. A sale can close right up until the auction, so the date on that notice is a deadline, not a door that already shut. What shrinks as it gets closer is the room to negotiate, not the option itself. Send me the notice and the payoff figure and I will tell you straight whether it still fits.

How long before foreclosure in California?

That clock is set by statute and by what your lender has actually filed, and I am not the one to read it for you, a foreclosure attorney or a HUD-approved housing counsellor is, and they will do it in one call. What I can tell you is the half I control: about 17 days at a local title company once you decide, so you know whether a sale fits inside whatever window they give you.

Can I sell my house in foreclosure?

Yes. Selling a house in foreclosure is ordinary work at a title company: the lender is paid out of the proceeds, the same as any other lien, and the process ends when they are paid. What makes it feel impossible is the calendar, not the sale. A distressed property is still a property, and mine is not the only offer you should get.

Will selling stop the foreclosure?

Closing the sale pays the lender, which ends the process. Signing a contract does not, by itself. That is why the closing date matters more than the offer date here.

What if I owe more than the house is worth?

Then a straight sale does not clear it, and you need your lender and your attorney in the conversation before you talk to me. I do not buy short sales as a rule, and I would rather say so now than waste three weeks of yours.

Do I have to pay the back payments before closing?

No. They are paid out of the proceeds at closing, through escrow, the same as any other lien.

Start with the address

Sell your house for cash in Los Angeles.

You’ll know all three numbers before I leave your kitchen. And if listing it the ordinary way is the better move for you, I’ll say so out loud.

  • No repairs, on any path
  • Nothing to pay for the visit
  • No obligation to take any of the three
Property address

Or skip all this:

(323) 363-2731

That’s my line. Maisha or I pick it up.